
Posted on 09/18/2026 9:08:06 PM PDT by SeekAndFind
“What the K-shaped economy gets right, what it exaggerates, and what believing the worst version is costing a generation.”
The bottom half of American households owns about 2.5% of the nation’s wealth. That number is real, and it ought to bother you. However, that number is also higher than it was in 2019 and 2015, and roughly six times higher than the 0.4% low it hit in 2011. You will not read that in many places because it doesn’t “fit the narrative.”
Unfortunately, the K-shaped economy headlines have settled into a single unvarying note, and after a while, people stop hearing anything else. I’ve spent the past several weeks working through the underlying data. While there is some truth to the coverage, most of the claims are exaggerated for “clicks and views.” But the psychological damage is clear.
So, before we get into our discussion, here are some numbers for you.

Let me start where the “Persistent Purveyors of Doom” crowd bases its argument, as there is indeed a K-Shaped economy. However, what is critical to understand is that the K-shaped economy is not new. In every economy throughout history, there has always been a K-shaped divide between those at the bottom and those at the top.
Nonetheless, as the headlines suggest, the wage compression of 2020 through 2023 was extraordinary. Autor, Dube, and McGrew documented it in their paper “The Unexpected Compression.” The 90/10 wage ratio fell far enough to reverse roughly a third of forty years of divergence.1 Then it stopped, and worse, it began running the other way.
The Economic Policy Institute data for 2025 show that real wages at the 10th percentile fell by 0.3%, while the median rose by 0.8%.2 The lowest-paid workers in America went from the fastest-growing group in the distribution to the only one moving backward.
However, the Cleveland Fed adds a detail that should end many K-shaped economy arguments. Between 2020 and late 2025, real wages at the 10th percentile rose 9.7% against 4.5% at the 90th. In dollars, that’s $1.34 an hour against $3.09.3 Percentage compression off a small base is not catching up. And the 2015 to 2020 dollar gains were LARGER at every percentile in the bottom half than the celebrated pandemic-era gains were.

The price level is also crucial to discuss, and is where I think most commentary goes soft. Inflation falling from 9% to 3.4% is a change in the rate, not the level. Since December 2019, consumer prices have risen by roughly 29% and have stayed there. That is a permanent shift in the cost of living, and it is the part of the K-shaped economy argument that sticks, and it hits households with no assets the hardest.
As I’ve written before, “wage growth as a leading inflation indicator” matters for policy. The level is where people actually live. McKinsey asked 30,119 Americans this April, and 60% named the cost of living as one of their top three barriers. That held even with those over $150,000 in income.

Furthermore, the hiring rate hit 3.1% in February 2026, the lowest reading outside the pandemic, while the share of unemployed workers for 27 weeks or more reached 27.5% in May. Separately, expiration of the enhanced ACA credits pushed average net marketplace premiums up 58% and average deductibles up 37% in a single year.4 That is a real, dated, 2026 hit to exactly the households everyone is arguing about.
The honest summary is that the ladder from the bottom of the K to the top got harder to climb, even as the rungs themselves stopped moving apart.
The single most repeated statistic in this entire debate, the one anchoring roughly every set of K-shaped economy headlines you have scrolled past this year, is that the top 10% of earners account for about half of all consumer spending.
It comes from Moody’s Analytics. The number is shakier than it looks. Moody’s revised its own estimate down from 49.2% to 45.8% after a methodology change, and Mark Zandi told reporters plainly that he “wouldn’t die on the hill of the top 10% accounting for 45% of the spending.”5 Berkeley’s Antoine Levy points out the arithmetic problem: the top decile takes home 35% to 40% of disposable income and saves a fifth of it, so its spending share cannot be half. The BLS Consumer Expenditure Survey puts the figure at 22.9%.

While you may think that is just economists arguing amongst themselves, it isn’t. What is crucial to note is that when the number that anchors the entire narrative varies by a factor of two depending on who computes it, that is a problem. In other words, the narrative is doing work the data cannot support. Such is the nature of a story that has outrun its evidence.
Furthermore, the perception gap runs deeper than just one statistic. In that same McKinsey survey, 56% of consumers named food as the category with the largest price increase in 2024.6 Here is why that is important. During that same period, insurance, housing, and childcare all rose faster, meaning that people are not tracking the data.
In other words, people are tracking what they hear on television and read on social media, and the two have become detached.
Here is where it gets interesting.
Everyone “knows” wealth concentration is worse than ever. As I laid out in my earlier piece on the K-shaped economy and why the middle class moved up, the income story runs in the opposite direction from the coverage.
The wealth story is stranger still. Pull the Federal Reserve’s Distributional Financial Accounts and compute it yourself, and the top 10% share of household net worth peaked at 70.3% in the first quarter of 2019. It sits at 67.9% today. The bottom 50% share bottomed at 0.4% in late 2011, was 1.7% at the end of 2019, and is 2.5% now.

When looking at wealth concentrations, it is very easy to blame those at the top of the wealth pyramid. Yes, the top 10% of the population held a 31.8% share of economic wealth in the fourth quarter of 2025. Yet the bottom half gains since 2019 came almost entirely from the 90th to 99th percentiles, which fell from 39.7% to 36.3%. In plain English, the professional class lost relative ground, not the working class. Such is a detail that changes who you think is complaining.
Furthermore, the recovery that no one called K-shaped was far worse. Between 2007 and 2016, median wealth for the bottom 30% of families fell 31% while the top 10% fully recovered.7 Saez found the top 1% captured 91% of real income growth from 2009 to 2012. Nobody ran a K headline in 2013. The data was uglier then.
The last false claim is the one that worries me most, because young people believe it about themselves. That is the real damage the K-shaped economy headlines have done. Vanguard’s administrative records show 401(k) participation among young workers at 54%, against 28% for the same age group in 2004. Savings rates are higher, and average balances have roughly doubled.8 Vanguard’s own model puts 47% of Gen Z on track to sustain their standard of living in retirement, seven points ahead of the boomers. The problem is NOT that young people stopped saving

McKinsey found the same thing from the other direction. Adults aged 18 to 24 face the worst entry-level labor market in decades, and 34% name mental health as their top barrier, against 14% of older adults. Yet they were more likely than any other older group to say their finances will improve and that their lives have momentum.
“The generation everyone is writing eulogies for has not read them.“
This is the question I actually wanted answered, so I went looking for the research. Does talking constantly about a K-shaped economy help create one? The answer splits cleanly in two, and almost nobody reports both halves.
At the level of the whole economy, no. The Chicago Fed published the number in June. The correlation between the Michigan sentiment index and annual real consumer spending growth ran 0.69 before 2020. Since 2020, it has been roughly zero.9 Their composite estimate says Michigan currently understates sentiment by 25 to 30 index points. About 10 of those points trace to the 2024 switch from telephone to online collection. Then there is the receipt test. A Fed study matched roughly 10,000 survey responses to verified purchase records. Some 43% said they were doing worse than in 2019. Most had actually bought more.

Secondly, Barsky and Sims settled the mechanism years ago: confidence is a leading indicator, not a cause.
In the economy, confidence carries information that people already have; in a survey, they respond to what they have read or seen, rather than to what they expect. This is also the structural reason why the doom loop can’t close at the macro level. Bank runs feed on themselves because if you withdraw your money, it makes my withdrawal smarter. However, in the economy, consumption lacks this property. Your neighbor skipping a vacation does nothing to make skipping yours a better idea. Such is why sentiment can collapse, and spending can increase.
At the level of one household, yes, and this is where it bites. The K-shaped economy doom loop is real. It just doesn’t run through GDP. It runs through the handful of large, irreversible decisions a person makes over a lifetime.
The clearest evidence comes from Bailey and co-authors. They matched 1.4 million Facebook users to 525,000 housing transactions, then used the house price experiences of geographically distant friends to isolate the belief channel. When distant friends saw 5 percentage points more price appreciation, a renter’s probability of buying rose 3.1 points off an 18% base.10 Beliefs picked up socially, from people nowhere near your housing market, changed whether you bought a house.
Now apply that to a young person marinating in K-shaped economy headlines. I’ve pushed back before on the lazy version of this story, the one painting a whole generation as financial nihilists. That framing is still wrong. The behavior at the margin has gotten worse anyway. Baker and colleagues at Northwestern, using transaction data on 230,000 households, found that every dollar wagered on sports betting reduces net household investment by about 99 cents.11 Not lottery spending. Not other gambling. Savings.
The damage compounds from there. New York Fed researchers found credit card delinquency rates rising 1.02 percentage points among households under 40 in states that legalized. Furthermore, separate work by UCLA and USC estimates that roughly 30,000 additional bankruptcies a year are attributable to online betting.12 The same restlessness shows up in the options tape. Zero-day contracts reached 65% of total SPX volume in May 2026. Citadel Securities reports that nearly half of all retail options volume on its platform now expires on the same day, up from 13% in 2021.
None of that is saving or investing, and it is the real culprit behind the “K-shaped economy” narrative. In other words, the narrative is driving behavior that is creating the outcome. As we documented in our work on why retail traders consistently underperform, the average retail equity investor earned 16.54% in 2024, compared with 25.02% for the index. The performance gap is due to behavior, not access.
While everyone agrees that the economy is hopeless for the young, the agreement itself is the tell.
Are there problems in the economy? Yes. Let’s recap what we know.

But here is the real question to ask yourself, particularly if you “feel” like your future is hopeless.
“Do you have the ability to change your outcome?”
That answer is unequivocally – “yes.” You just have to be willing to do the work.
First, fix your benchmark. You are not competing with a stranger’s vacation photos or the top 1% of a country of 340 million people. The relevant comparison is your own plan, and whether this year moved you closer to it. Everything in thinking like an investor rather than a speculator starts there. McKinsey found Americans with strong community ties were nearly four times as likely to feel their lives have momentum. Only a third felt they were connected. Trade some screen time for the other thing.
Second, stop gambling and call it what it is. Nobody ever bet their way out of the K-shaped economy. Will a sports parlay occasionally pay off? Sure. Will it build wealth over 30 years? The data is very clear that it doesn’t. More notably, the ones betting are also the ones who can least afford it.
Third, set goals you can actually hit. The $1.46 million “magic number” that circulates every January is a survey artifact from a company that sells retirement products. It is not your number. The number you need to focus on comes from your spending, your timeline, and your obligations, which is a smaller and far more solvable problem than headlines imply.
Fourth, automate the boring parts. The reason that Gen Z is projected to retire better than the boomers is not superior discipline. It is auto-enrollment. Company 401 (k) plans that enroll workers by default have a 94% participation rate, compared with 64% for voluntary plans. Design beats willpower, every time.
On housing, I recently argued that home affordability is better than the headlines suggest, and that holds for the monthly payment burden. Harvard’s housing center set home prices near five times the median income, up from roughly three times in the 1990s. That is indeed a barrier to entry.
However, the down payment for homes today is 3% versus 20% in the 1990’s. So, yes, the payment is manageable once you’re in, but the hard part is saving up for the down payment. I get that, and here is the hard truth. If you can’t save up a 3% down payment, you have other financial problems (e.g., overspending) that you need to resolve first. The mortgage payment is one thing; the taxes, fees, maintenance, and everything else that goes with the joy of homeownership is quite another.
The K-shaped economy is real, and it is old. What changed isn’t the shape of the economy; it’s just that the media found a narrative that gets lots of clicks and views, and we let headlines do our thinking for us.
Believe the headlines, and you will make exactly the decisions that guarantee they come true for you.
* * *

|
Click here: to donate by Credit Card Or here: to donate by PayPal Or by mail to: Free Republic, LLC - PO Box 9771 - Fresno, CA 93794 Thank you very much and God bless you. |
I guess I’ll just remain ignorant because I don’t know what a “K-shaped” economy is and the article does not start out explaining that or do it anywhere else I could see in a quick scan. No time for something like that.
This is a small part of what is driving GenZ to go crazy. They believe the perception. The media lies to them and they gobble it up.
RE: I don’t know what a “K-shaped” economy is
In simple terms, A K‑shaped economy is a way of describing an economic situation where different parts of the economy are moving in opposite directions at the same time — one group is doing well, while another is struggling.
So, Why is it called “K” shaped?
Look at the letter K, with one arm going up and the other going down.
If you graph the performance of these two groups over time, the lines diverge — one going up, the other going down — much like the two arms of the letter “K”.
In simple terms:
Upper “arm” of the K: Certain sectors, industries, or people (often higher‑income households, asset owners, or in‑demand professions) are experiencing strong growth, rising incomes, or increasing wealth.
Lower “arm” of the K: Other sectors, industries, or people (often lower‑ and middle‑income households, service workers, or those in declining industries) are seeing stagnant wages, falling incomes, or rising costs.
These two paths happen at the same time in the same economy, so the overall picture is split rather than uniform.
I hope this helps.
This is a small part of what is driving GenZ to go crazy. They believe the perception. The media lies to them and they gobble it up.
*****************
The media may be lying to them, but that isn’t the reason the younger generation doesn’t like the current economic system.
What they don’t like is the current asset inflation vs their income, which is so out of line from a historical perspective that it’s mind boggling. Eventually they’ll be a breaking point economically between the two positions, and a more favorable economic alignment will take place.
However, we aren’t there yet, so “economic disgruntlement” will continue in the near future.
It's especially egregious with politicians lasting beyond two terms. One obviously "plays ball" (regardless of party label) or you end up shut out short of resources and having to pack it in. If you Play Ball - "reaching across the aisle" to help enemies pass tax-thieving legislation - you get to live another round while thrown bones like offshore investment havens and sure-fire stock picks.
Corruption by drips and drabs until you're an utterly compromised tool of the worst people running government. I'm convinced there's concerted programs to tempt newcomers, amass material proof of their weaknesses and use that to blackmail them into submission, with wagers among the corruptors over how long it takes to do it.
Like Mortimer and Randolph in the movie "Trading Places" betting a dollar.
With obvious back-dealing going on widening the gap between the well-off and the hard workers scraping by no one should be surprised that this current generation is resentful for being shut out of home-buying, higher education without massive debt and hope for the future - especially painful seeing loop-holed legal immigrants drying up gainful employment and illegals gaming the system on their tax money.
The inflation is also a part, but the biggest chunk of the pie is Social Security.
GenZ has rightfully picked up on the fact that old Americans steal from young Americans and Social Security is the vehicle, the “how”.
Most of the hatred GenZ has for Boomers can singly be placed on the shoulders of the Social Security program. Add in inflation as well as ideas such as this K-Shaped Economy and we’ve got a powder keg on our hands ready to explode. Oh and also GenZ is also indoctrinated in the government schools to generally hate the U.S. So they don’t want it anyways - they think it sucks and they think its racist. That is what they were all taught, hate America.
I just heard the term “i” shaped economy for the first time, from housing analyst Melody Wright.
There is the small group of haves getting richer and then there is the rest of us getting poorer.
Rich getting richer and poor getting poorer. Middle class has gone. I’m one of millions on a fixed income(except COLA) and I have lost so much in the past five years. It keeps getting worse.
Social Security isn’t simply money that Boomers took from Gen Z. Older Americans generally paid Social Security taxes during their working years, and benefits are determined by a statutory formula based substantially on lifetime earnings and years of covered employment.
Calling that “stealing” changes an economic description into a moral accusation.
What you stated is. not a fact. It is a perception. I have paid into SS over 45 years at high levels. When I start to recieve some back it is not stealing.
*******************************************************
“GenZ has rightfully picked up on the fact that old Americans steal from young Americans and Social Security is the vehicle, the “how”.”
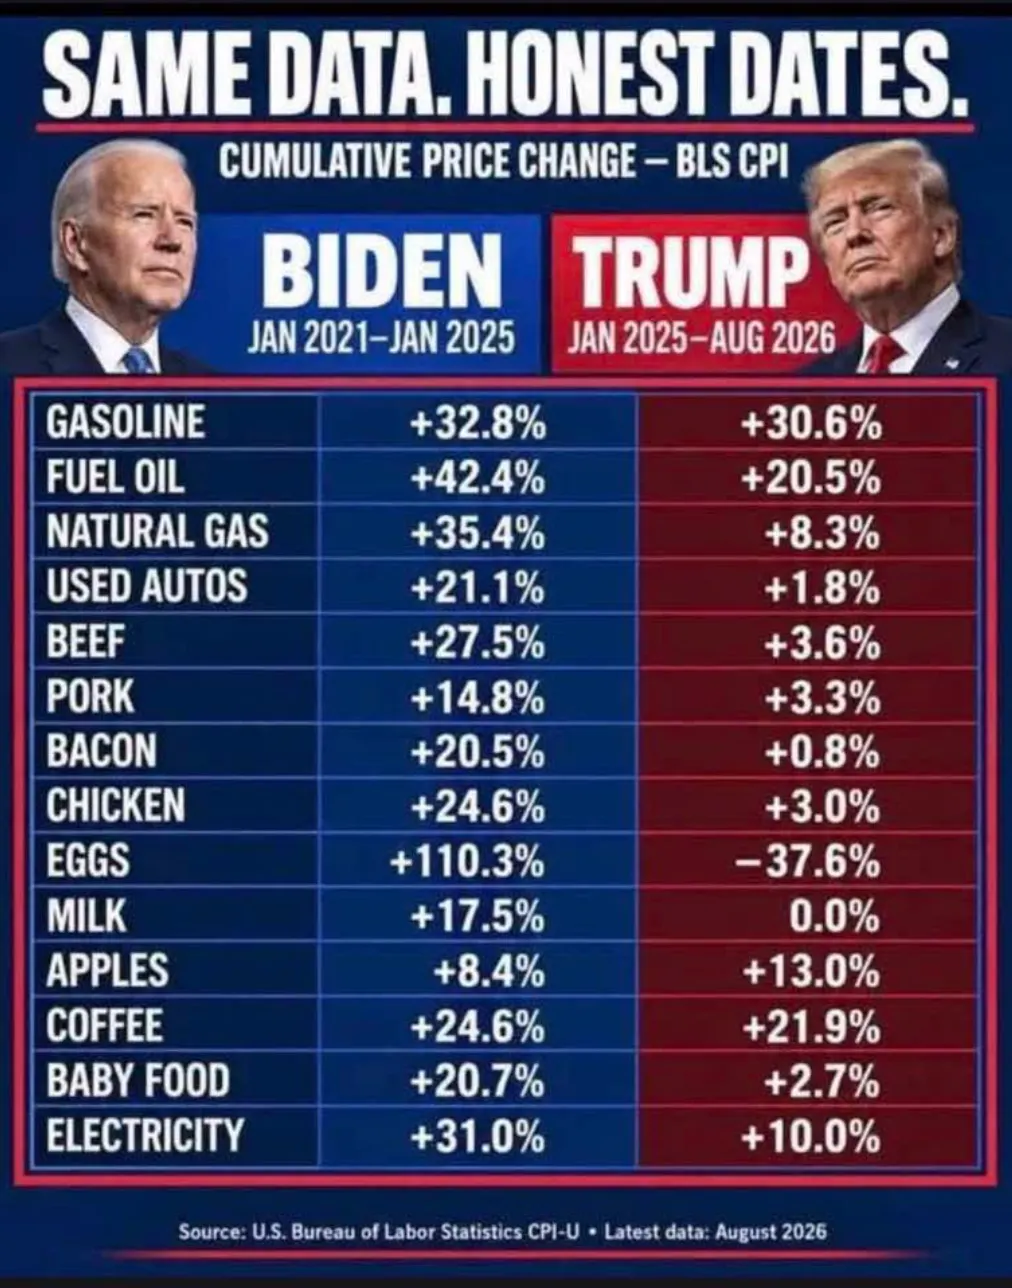
Based on that graph, and the fact it states ‘cumulative’, then Trump this term has also raised prices. Sure, it the amount may be smaller than Biden’s increase, but Trump’s just build on Biden’s.
So if that premise holds true, Trump has nothing to brag about. Economically, I’m not convinced there’s a lot to be proud about this term.
The school indoctrination has been going on for longer than Gen Z has been alive.
Kids knew way back in the 1980’s they were being taught a load of BS. So when they took exams they’d just regurgitate the BS to get a passing grade.
Much of the disillusionment you see is the lack of job prospects for young people.
The Ludwig Institute for Shared Economic Prosperity found that 24.9% of American workers are unemployed, working multiple part time jobs or are below the poverty line.
The government has over the years adopted policies and laws that throw the advantage wildly in favor of employers such that American born workers have virtually no bargaining power.
RE: Sure, it the amount may be smaller than Biden’s increase, but Trump’s just build on Biden’s.
It depends on the baseline by which you measure price increases against. I’m trying to understand the chart, how is for example, electricity at +10% under 18 months of Trump determined? Was it based on what the price was was BEFORE Biden was elected? AFTER? What year are we measuring it against?
If electricity in 2020, the price was $X per KWH and Biden’s administration spiked it to 38% above $X, then along came Trump, and it came down to only 10% above $X, then that’s an improvement. Sure, it still leaves much to be desired, but the trend is down. Perhaps more time us needed for the downward trend to continue. You don’t undo ALL 4 years of forced green energy on the economy ( including the cancellation of the Keystone pipeline) in just 18 months.
If people use this to say that Trump hasn’t improved things, think about where we’d be today with a President Kamala Harris.
Look,
We all know that Social Security is a Ponzi Scheme. That is not new information.
Yes, we all have paid into it *some*. But we aren’t just going to receive back *some*, we aren’t just going to receive back our money and only our money. We will end up receiving other people’s money.
The “other people” - the victims, are perfectly and legitimately aggrieved by this. They are, actually, in fact, victims here. They are. 100%. This is not arguable. They are victims.
They shouldn’t lose their money any more than you should lose your money but the fact that you couldn’t give a damn about anybody else’s but your own is precisely the problem we face with GenZ.
GenZ is not wrong. And that’s why they aren’t stopping. They’re not wrong. Why should people who are correct have to stop? That’s a ridiculum.
GenZ + Margaret Thatcher is once again proving the old addage of the problems societies face when you start running out of other people’s money.
And dammit FDR did this to us. It was only a matter of time before his whole system caused a generational war; old fighting young. The young generation who gets pissed about being stolen from, and the old generation who says they deserve it based on what they paid while simultaneously ignoring the portion of the paybacks which are not legitimately yours. If you are receiving someone else’s money then the fact is you’re receiving too much money, not what you paid in.
FDR did this. The old vs young war is here.
The indoctrination is not new, true.
However every year progressives dial the notch just a little.
What I mean is that the indoctrination I received is not the same as the indoctrination that you received - and it really is not the same as the indoctrination that GenZ received. And all of it is not the same as the indoctrination that the Silent Generation received decades ago.
And the indoctrination that GenZ received? That’s nothing compared to what Generation Alpha is currently receiving and that?
Wait until Generation Beta gets here. And the indoctrination will be worst of all for Generation Gamma. Except until Gen Delta gets here.
Just because information is being regurgitated to get a grade, doesn’t mean that information isn’t sticking around because in the mean time nature abhors a vacuum. If you have only spent time memorizing ideological information there’s no time left for truth. In other words, this is why progressives still win anyways. The regurgitators are still advancing progressivism anyways because its the only information on the table at all.
I forgot to say thank you for your good and helpful explanation.
Writers seem to more frequently launch into stories about some things as if they are common knowledge whan they are frequently not.
This is like all commie trash/woke articles — written ‘cause if they don’t they don’t get paid. Doesn’t matter if no one either reads it or understands. This is not about communication, it is about speaking.
AS to prices, it is all supply/demand. Illegal aliens spike housing prices by 30%. Many are also subsidized by gov’mt. Get rid of all 20M of them and prices on EVERYTHING will crash in weeks.
Disclaimer: Opinions posted on Free Republic are those of the individual posters and do not necessarily represent the opinion of Free Republic or its management. All materials posted herein are protected by copyright law and the exemption for fair use of copyrighted works.